The perfect AI credit model has been nearly here for a decade. Feed it enough data or train it for long enough, and it will (finally) score everyone fairly – or so the sales pitch goes. It won’t. It can’t. And aiming for this is a problem, because an industry sprinting after algorithmic perfection is an industry automating its own worst habits.
Now, I’m a founder of a fintech that lends to customers that banks won’t, so I’ll declare my interest early, but I spend my days on the wrong side of these models’ rejections – and what I see from where I sit should worry every lending boss in the country.
Garbage in, sweet gospel out
Here’s the problem that no one puts in the slide deck: Most AI credit models are trained on historical bureau data, and that data is a record of who was given credit in the first place, not a neutral account of who repays. Train a model on it and you don’t get objectivity. You get the past, replayed at speed, with all its blind spots intact.
Who sits in those blind spots? Renters who’ve never held a mortgage. Immigrants with thin UK files. Gig workers whose income arrives in irregular lumps rather than a tidy monthly payroll ping. The bureau file says “too risky”. The model, over-fitted on decades of that assumption, agrees – only faster, at scale, and with a confidence score attached.
The result? 5.6 million Britons who are invisible to the credit system despite paying taxes, holding jobs and running businesses. No credit history means no credit, and no credit means no history. Fair4All Finance puts the cost of that exclusion at £6.4 billion a year to the UK economy.
A £6.4 billion mistake. And the training data inspired it.
Look out of the window
Now, playing devil’s advocate: nobody chose bad data out of malice. Bureau scores were the best tool available for half a century, and the caution behind them is genuine – consumer lending is a regulated business, and it should be. However, defending the bureau file in 2026 is defending last month’s weather report when you could simply look out of the window.
The window is the bank account. Assess affordability from actual transaction behaviour, shared with consent through open banking, and a different picture of risk appears. Borrowers the bureaus reject routinely repay as well as “prime” cohorts, and sometimes better. The 22-year-old graduate on £28k who has never owned a credit card is frequently as safe as the applicant with two maxed-out cards and a 680 Experian score. One of them just never performed the ritual dance of credit-building.
The questions worth asking of a bank statement aren’t mysterious. What share of someone’s income is already committed to subscriptions and recurring bills? How consistent are their financial commitments – a signal bureau models simply cannot see? Does their balance swing because they are genuinely stretched, or because they’re a gig worker with irregular but reliable income? What non-payroll earnings does the median income transaction reveal that a bureau file never records? And what do they actually spend against what they actually earn, measured from behaviour rather than a self-reported form?
None of this is exotic – it’s cold mathematical reality about actual money. The exotic part is that most of the industry still isn’t reading it.
Let the dishwasher do the dishes
So should lenders hand the whole decision to a machine? No. The sharper question for anyone running a lending business is which decisions a model should govern and which it must never own.
AI has earned the pattern-heavy, high-volume work: classifying transactions, spotting anomalies, parsing documents, monitoring how predictions track against real-world repayment. Machines beat humans at all of it, and automating it frees people for the work that genuinely needs them. Let the dishwasher do the dishes.
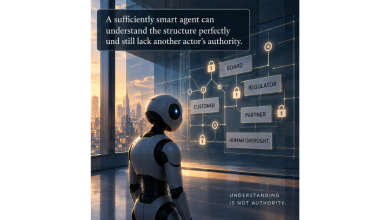
But nobody lets the dishwasher plan the menu. Human judgment stays wherever accountability lives: edge cases, vulnerability indicators, model governance, the decision framework itself. And no credit model should be signed off once and forgotten. Treat every version as a living system, monitored against actual repayment outcomes, with a documented line marking where the model’s authority ends and a human’s begins.
Show your working
In consumer finance, “the algorithm said no” is not an answer. Not to a customer. Not to a board. And certainly not to the Financial Conduct Authority (FCA), at a time when black-box AI is under growing regulatory scrutiny.
A lender that can’t show its working can’t evidence fair treatment, can’t diagnose drift and can’t defend a challenged decision. Explainable models flip that liability into an asset. Documented, explainable features mean you can show the regulator precisely why an application was approved or declined – and show the board the return: fewer defaults from better-calibrated affordability, access to a 5.6-million-person market your competitors can’t score, and a compliance posture that survives an audit rather than dreads one.
No agent, model or API will fix a credit system whose failures are decades old. But AI that reads real behaviour, answers to humans and shows its working can finally see the people that the system has been ignoring. Five and a half million of them are waiting.
Someone should look.