A finance team can usually explain why an employee approved a payment or rejected an invoice. Not only is there a person attached to the decision, but there is a process and often a trail of documentation that can be followed months later if questions arise. That becomes more complicated when software starts making the decisions.
Artificial intelligence is now remarkably good at handling the kinds of repetitive tasks that once consumed finance departments. It can classify invoices, identify anomalies, route approvals, recommend actions, and increasingly resolve issues without human intervention.
However, technical capability is no longer the sticking point. The argument now centers on authority. How much decision-making power should organizations hand to software, and how much accountability should remain with people? That question sits at the center of a growing debate inside enterprise finance.
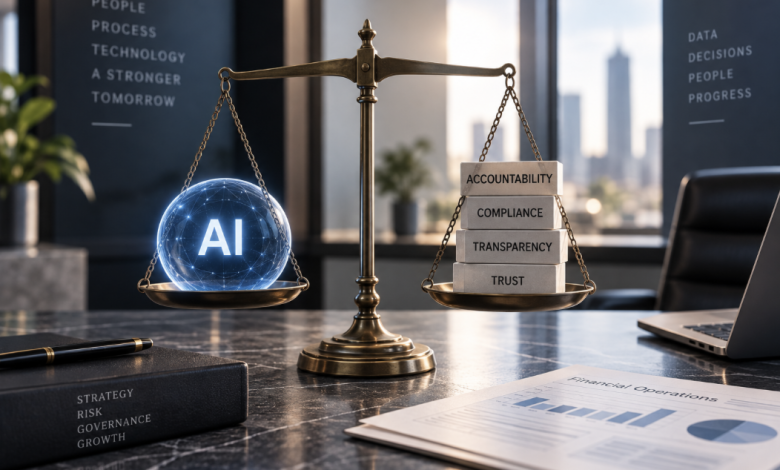
Boards want companies to move faster with AI, and finance leaders are being asked to find productivity gains. Regulators and auditors, meanwhile, are asking a different set of questions about transparency, accountability, and control. The result is tension that many organizations are still trying to resolve.
According to Gartner research, only 36% of CFOs feel confident in their ability to generate meaningful enterprise impact from AI initiatives. That figure stands in contrast to the enthusiasm surrounding the technology and suggests that adoption and confidence are not necessarily moving at the same pace.
Jason Kurtz, Chief Executive Officer of Basware, sees that disconnect regularly. The company serves more than 6,500 organizations globally and has spent more than four decades focused on invoice lifecycle management, giving it a front-row seat to how finance teams are approaching AI adoption.
“Every CFO I talk to has the same problem,” Kurtz said. “Their board wants them to use AI. Their auditors want a trail of accountability for every decision that touches the books. Their teams want to know exactly what AI is allowed to do and where they still have the final word.”
The distinction matters because finance teams are increasingly being asked to trust AI with actions rather than suggestions.
Many organizations have already become comfortable with systems that surface insights or suggest next actions. Allowing software to actually perform work inside financial processes introduces a different level of scrutiny. An incorrect recommendation can be ignored, but an incorrect action can create operational, financial, or compliance consequences.
For Basware, the more important question is no longer what AI can do, but how much authority organizations are willing to give it.
The company recently introduced what it calls the Governed Autonomy Framework for Finance, an operating model designed around a simple premise. Organizations should decide not only whether AI participates in a process, but also how much authority it is granted within that process.
Under the framework, AI can function as an advisor that makes recommendations, a collaborator that operates within predefined policies and thresholds, or an operator that executes work autonomously within customer-defined controls. The objective is not to move every organization immediately toward full autonomy but to instead create a structure that allows authority to expand gradually as trust and confidence increase.
Kurtz puts it plainly: “Think of it like onboarding a new hire. You do not hand a new AP clerk authority over millions in spend on day one. You set guardrails. You watch how they perform. You expand their authority when they earn it. Governed Autonomy applies the same logic to AI.”
Much of the discussion around enterprise AI focuses on finding the right balance between autonomy and oversight. Donna Wilczek, Chief Product and Technology Officer at Basware, believes the relationship is less adversarial than it is often presented.
“I would challenge the idea that this is a trade-off,” Wilczek said. “Oversight is not the thing you trade against autonomy. Oversight is what earns autonomy. The more observable and traceable a system is, the more autonomy you can safely hand it.”
That idea appears repeatedly throughout enterprise AI discussions, although often under different terminology. Organizations that succeed with AI rarely do so because they eliminate controls. More often, they create systems capable of generating enough evidence, transparency, and auditability that additional automation becomes acceptable.
In finance, that requirement is particularly difficult to ignore.
An AI model may achieve impressive automation rates, but automation alone does not satisfy auditors, regulators, or risk teams. Financial decisions require organizations to explain how a conclusion was reached, what information was considered, and who ultimately remains accountable for the outcome.
“In a regulated finance function, automation isn’t enough on its own,” Wilczek said. “You have to show your work. A model that’s 99% accurate but can’t tell an auditor why it made a call is unusable for anything that actually matters.”
Those concerns are becoming increasingly relevant as regulatory requirements continue to expand. France’s e-invoicing reforms, Poland’s KSeF framework, Germany’s B2B e-invoicing requirements, and the European Union’s VAT in the Digital Age initiative are all reshaping the compliance landscape for multinational organizations. At the same time, new AI governance frameworks are placing additional emphasis on accountability and documentation.
For Wilczek, compliance cannot be treated as something added after the fact.
“Everyone is working to teach AI what it can do,” Wilczek said. “The harder problem is teaching it what it must never touch. The models aren’t the differentiator; the data is. Any vendor can build an agent. Not every vendor has seen two and a half billion invoices flagged, corrected, and learned from. That is where the accuracy comes from. And without that accuracy, delegating authority to AI is not a business decision. It is a gamble.”
That reality is reshaping the build-versus-buy discussion across enterprise finance.
Organizations can increasingly develop capable AI agents, but scaling them inside business-critical processes requires data, controls, oversight, and accountability frameworks that are often far more difficult to create than the intelligence itself. In enterprise finance, trust has become a prerequisite for autonomy.
That perspective reflects Basware’s position that governance should be embedded into the operational foundation of AI rather than layered on top of it later. The company says its platform has been trained on more than 2.5 billion invoices and now supports more than one billion AI actions annually across its customer base.
That depth of data is not incidental. The data is what makes it accurate enough to trust, and accurate enough to extend that trust further over time. Models are increasingly commoditized. The data that trains them is not. A newer entrant may have capable agents, but without years of production data across real enterprise finance workflows, the accuracy required to delegate meaningful authority simply isn’t there.
After more than four decades focused on invoice lifecycle management, Basware argues that understanding where AI should stop can be just as important as understanding where it should act.
The broader implication extends to the many organizations still focused on deploying AI. Eventually, they will need to govern it. The companies that successfully make that transition will likely discover that trust is not created by reducing oversight, but by making decisions easier to understand, easier to trace, and easier to defend.
Finance teams have spent years evaluating whether AI can perform the work. The next phase will be determining how much authority they are willing to grant it, and what evidence they expect in return. The CFOs who answer that first will not just be ahead of their peers. They will be the ones their boards, auditors, and regulators trust most. That is not a technology advantage. It is a governance one.