Consider a backend developer in Bogotá who bills a Toronto startup in U.S. dollars every other week. The payment lands in a digital wallet and sits there while she weighs whether the peso is about to slide again.
Eventually it becomes rent, groceries and a set-aside for her next payment to Colombia’s tax authority. Every one of those steps is a decision a corporate treasurer would recognize, and she makes them alone, guided by whatever her apps can tell her.
What those apps can tell her has changed quickly. Stephan Tschabold, Chief Compliance & Risk Officer at Ontop, which handles payments for remote contractors, remembers how little was available not long ago.
“A few years ago, a contractor invoicing in USD, getting paid in a wallet, and spending in pesos had no real-time view of what any of that meant,” he says.
Workers like her used to learn what a month of work was worth only after the conversion had gone through. Now they can watch the number move before they act.
Tschabold’s wider view of the market is more mixed. At the large remittance and payments companies, he says, most of the AI money in 2026 is going into internal work: cheaper operations and faster product releases. He points to an argument gaining ground in payments commentary, which holds that AI’s real contribution to a cross-border transfer is making an existing trust corridor computable.
It can reconcile names, transliterations and intent between two parties who already have reason to deal with each other. It cannot create trust where none existed. For the developer in Bogotá, that means her tools have become far better at reading her situation than at changing the systems her money passes through.
The part that already works
Tschabold is unambiguous about where AI is earning its place. Cash-flow forecasting, automatic categorization of spending, and alerts that suggest a good moment to convert currency all give a worker a live picture of money spread across more than one currency.
Tax-readiness features and fee guidance built around a person’s own payment history belong in the same group. “That’s shipping today and it’s genuinely useful,” he says.
For anyone earning across borders, the habit worth forming is simple enough: turn on FX alerts and forecasting on every platform that offers them, and look at the monthly projection before deciding when to move money from dollars into the local currency.
The usefulness drops off sharply once a question involves two legal systems. “Most AI financial tools were built for a single-country user, one currency, one tax authority, one bank,” Tschabold says. “The intelligence layer is ahead of the infrastructure layer.” An app can track income to the minute and still have nothing to say about reconciling what a worker owes in two countries at once.
The gap gets wider when people move. A contractor with five years of steady, documented income can arrive in a new country and look unbanked, or even high-risk, because her earnings, tax filings and credit history live in separate systems with no connection between them. Tschabold describes a portable financial identity as the largest open opportunity in the space. Until a provider builds one, the practical answer is to build it by hand: invoices, tax returns, platform payment records and bank statements, kept together and ready to show a lender somewhere new.
When a normal transaction raises flags
Cross-border workers have spent years on the wrong end of fraud systems. Older rule-based screening flagged anything unfamiliar, such as a payment from a country the system had not seen before or a transfer at an unusual hour. Tschabold notes that this pattern is “exactly what a legitimate contractor’s normal life looks like.” The cost showed up as declined payments and frozen accounts for people who had done nothing wrong.
Newer models look at a broader set of signals, including transaction velocity, device data, relationship history and how consistent a person’s behavior is over time, and issuers using them report fewer false positives. That makes a provider’s screening approach a fair question to ask before signing up.
A worker can help her own case by staying on the same devices and keeping a predictable invoicing rhythm, which gives a behavioral model less to question. She should also expect tougher identity checks when opening accounts, since synthetic identities and deepfake voice scams are rising along with cross-border fraud.
Regulation has started to catch up, though unevenly. In August, the EU AI Act‘s obligations for high-risk systems took effect, and that category includes fraud detection, anti-money-laundering monitoring and credit scoring. Those systems must now be explainable, auditable and subject to human override, with liability resting on the institution that deploys them. A worker whose account is frozen or whose loan application is refused by such a model can ask for an explanation and a human review.
Outside that framework, the picture changes. Europe’s revised payments rulebook, which moves liability for authorized push-payment scams onto providers, is not expected to take full effect until late 2027, and FinCEN in the US is still working through its AML proposal.
“A worker’s payment can be legally high-risk AI in one jurisdiction and functionally unregulated for the identical use case in another, in the same corridor,” Tschabold says. Independent workers seldom have an employer or a relationship manager to push back on their behalf, so knowing which regulator each provider answers to is part of choosing one.
Who answers when it breaks
The fully autonomous AI financial advisor, in Tschabold’s assessment, remains mostly hype. The pattern recognition is capable enough. What nobody has resolved is who carries responsibility when an algorithm makes a bad cross-border tax or investment call. Visa, Mastercard and Alipay are all building infrastructure for payments between AI agents, and even they describe mainstream use as some distance away.
In the meantime, the setup that holds up best has AI suggesting a better moment to convert or flagging a tax obligation early, and the worker approving anything with real consequences. A slick interface says little about whether a platform will stand behind its decisions. “The deeper risk is that speed gets mistaken for credibility,” Tschabold says. The developer in Bogotá would do better to ask each provider who is accountable when something goes wrong, because in his view “AI-powered” still has to mean human-accountable.
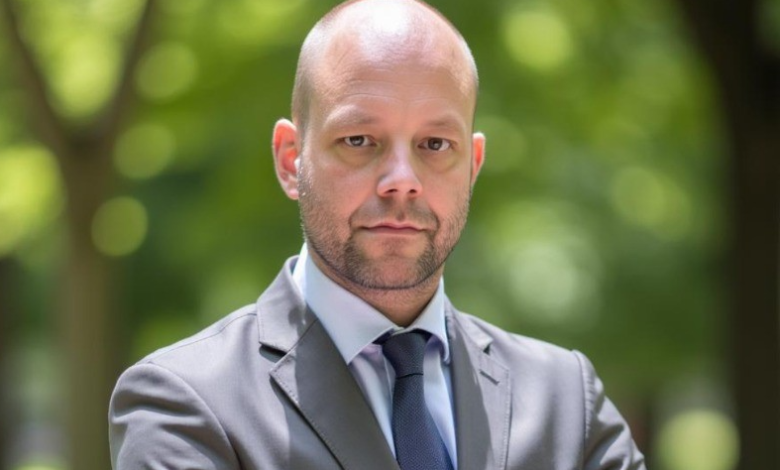
Article’s featured photo of Stephan Tschabold, Chief Compliance & Risk Officer at Ontop