Most information-return errors are not found by the people who made them. They are found by the IRS, months later, as a CP2100 notice, a rejected ACA transmission or a penalty letter that prices each mistake at $340 for the return and another $340 for the payee statement. By then the contractor has moved, the payroll clerk has changed jobs and the fix costs more than the form ever did.
The alternative is unglamorous: find the error while it is still a row on a screen. That is where automation has always earned its keep in tax compliance, and it is where AI is now adding something rules alone could not. This article sets out what each one actually catches, where the limits are, what the law expects of a firm that puts taxpayer data through an AI tool, and what a compliant process looks like in practice, using our own platform, TaxFormHero, as the worked example.
The five errors behind most rejections and penalties
Information returns fail in a small number of predictable ways. The table below covers the five that account for most of the notices we see, and what each one costs once it has been filed.
| Error | What it looks like | What happens if it is filed |
| Name/TIN mismatch | A vendor’s trade name on line 1 of the W-9 with the owner’s SSN, or a transposed digit in an EIN | CP2100 notice from the IRS, a B-notice to the payee within 15 business days, 24% backup withholding, and the $340 + $340 penalty |
| Missing W-9 data | No TIN, no tax classification, or an unsigned form, so nobody can say whether a 1099 is even required | A return filed with the TIN blank is penalized unless the payer can show dated solicitations |
| Wrong form or threshold | Rent reported on 1099-NEC instead of 1099-MISC; a $1,900 contractor filed under the 2026 threshold of $2,000; attorney fees in the wrong box | Unnecessary or incorrect returns, each of which needs a correction |
| Duplicates and splits | “Bright Field LLC” and “Brightfield, L.L.C.” kept as two vendors, so each falls under the threshold, or one vendor counted twice | Under-reporting in the first case, a double 1099 and an unhappy contractor in the second |
| ACA code combinations | A 1095-C showing an offer of coverage for all twelve months to an employee hired in July, or a line 14 code paired with a line 16 code that cannot coexist | Rejected or “accepted with errors” from the IRS AIR system, and exposure under section 4980H |
W-2 forms add a sixth, arithmetical class: Social Security wages above the annual wage base, or box 1 and box 3 figures that cannot both be right for the same employee. What all six have in common is that they are detectable before transmission, with data the filer already holds.
What rules catch, what TIN Matching catches, and what AI adds
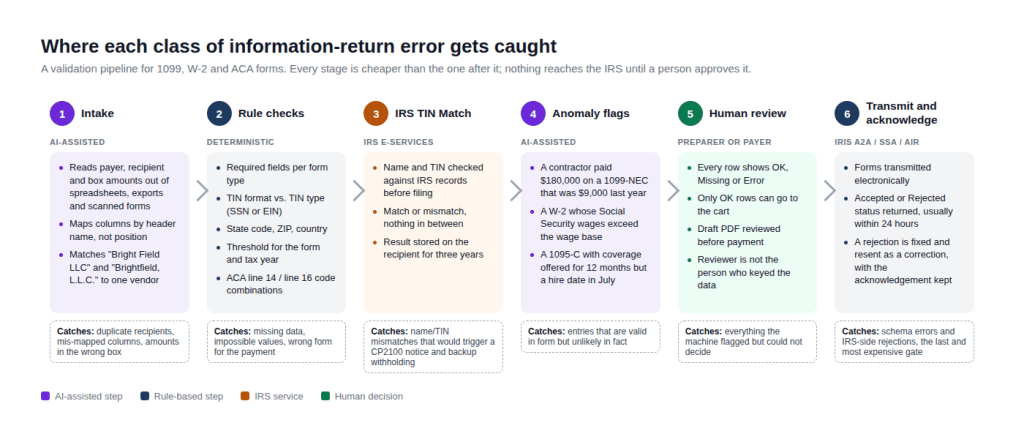
Figure 1. A validation pipeline for information returns. Each stage is cheaper than the one after it, and nothing reaches the IRS until a person approves it.
Rule engines are the oldest form of automation in this field and still the most valuable. A rule knows that a 1099-NEC needs a recipient TIN, that an SSN has nine digits in a 3-2-4 pattern, that a two-letter state code has to exist, that the 2026 nonemployee-compensation threshold is $2,000, and that certain ACA line 14 and line 16 codes cannot appear together. Rules are fast, explainable and never wrong about the thing they check. They are also blind to everything they were not written for.
IRS TIN Matching is the one check that uses the IRS’s own data. Through e-Services, a payer can submit a name and TIN and learn whether the pair matches IRS records: up to 25 pairs interactively, or up to 100,000 in a bulk file. The answer is binary. No amount of local validation can substitute for it, because the question is not whether the TIN is well-formed but whether the IRS agrees it belongs to that name. On TaxFormHero the IRS TIN Match is offered as a paid add-on with the filing, run on the payees the filer selects, and the result stays on the recipient record for three years.
AI earns its place in three jobs that rules handle badly. The first is intake: reading payer, recipient and box amounts out of a spreadsheet whose headers do not match the template, a vendor export from an accounting system, or a scanned W-9. The second is entity resolution, which is a formal name for noticing that two vendor records are the same company. The third is plausibility: a rule cannot say that a $180,000 payment to a contractor who received $9,000 last year is odd, because it is a valid number in a valid box. A model trained on the shape of normal filings can flag it for a human to look at. In each case AI proposes and a person decides.
The 2027 deadlines these checks have to beat
Tax year 2026 forms are filed in early 2027. January 31 falls on a Sunday, so the January deadlines move to Monday, February 1.
| Form | Copy to recipient or employee | Filed with the IRS or SSA (electronic) |
| 1099-NEC | February 1, 2027 | February 1, 2027 |
| 1099-MISC (no box 8 or box 10 amounts) | February 1, 2027 | March 31, 2027 |
| 1099-K | February 1, 2027 | March 31, 2027 |
| W-2 | February 1, 2027 | February 1, 2027 (SSA) |
| 1095-B and 1095-C | March 2, 2027 | March 31, 2027 |
Three rules sit behind the table. A filer with 10 or more information returns of any type combined must file electronically, which in practice means every employer and most small businesses. The IRS FIRE system accepts its last filings on November 19, 2026, so January 2027 returns go through IRIS, and anyone still holding prior-year data in the Publication 1220 fixed-width format will need it as a spreadsheet first. We publish a free FIRE file converter for that: it turns a Pub. 1220 file into payer and recipient CSVs, runs entirely in the browser, and uploads nothing, so a file full of live SSNs never leaves the user’s machine. And no automatic extension exists for 1099-NEC or W-2; a late one is simply late.
What the same error costs at each stage
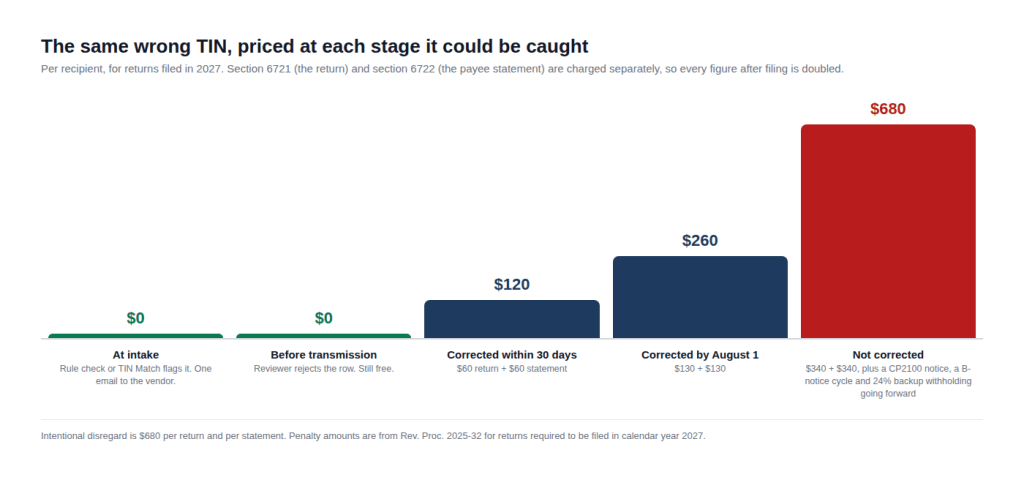
Figure 2. One wrong TIN on one recipient, priced at each point it could have been caught. Section 6721 and section 6722 penalties are charged separately.
The chart is the whole argument for validation. A mismatch caught at intake is an email to the vendor. The same mismatch caught after filing is at least $120 if it is corrected within 30 days, $260 by August 1, and $680 if it is never corrected, before the B-notice cycle and the 24% backup withholding that follows. Multiply by the number of recipients in a batch and the case for checking before transmitting makes itself.
How it runs in practice
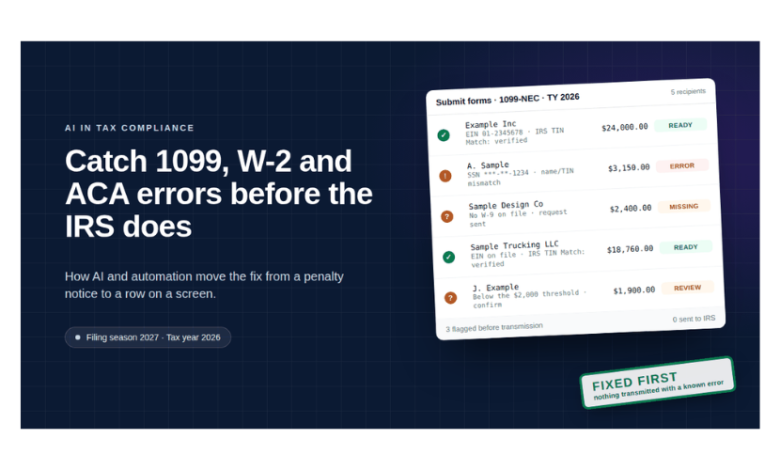
On TaxFormHero the sequence follows Figure 1. A filer either types recipients into the dashboard or uploads the Excel template for the form; columns are mapped by header name rather than position, so a reordered or trimmed sheet still imports. Validation warns rather than blocks: the file loads with every problem listed, and the only hard rule is that an SSN or EIN must be present. Every row then carries an OK, Missing or Error flag, and only rows marked Ready can be added to the cart. The filer reviews the draft PDF of each recipient copy before paying, and after payment the forms go to the IRS over IRIS A2A, with Accepted or Rejected status back in the dashboard, usually within 24 hours. A rejection is fixed on the same screen and resent as a correction.
Two services close the gaps the table above describes. Where a W-9 is missing, the filer can Collect W-9 electronically: the vendor receives a signing link, completes the form online and signs under penalties of perjury, and the completed record lands in the recipient list rather than an inbox. Where a TIN is doubtful, the filer can add the IRS TIN Match for that payee at checkout, and the result is shown on the row. The combination means a batch of 1099-NEC forms can be built, validated and e-filed in one sitting, with the expensive errors surfaced before anyone pays for anything.
Do’s and don’ts for AI in information-return filing
| Do | Don’t |
| Use AI to read, map and reconcile data, and show the source for every value it extracted | Let a model fill in a TIN, an amount or a tax classification it could not find in the source |
| Run the IRS TIN Match on every new or changed payee before the return is built | Treat a well-formed TIN as a verified one |
| Keep a person who did not key the data as the approver, and require approval before transmission | Set up any path where a return reaches the IRS without a human decision |
| Give the model the current rules: the $2,000 threshold, the 2027 dates, the current W-9 revision | Assume a model knows this year’s thresholds; most were trained on the $600 era |
| Treat an AI vendor as a service provider under the FTC Safeguards Rule, with a contract that covers encryption, retention and no training on your data | Paste recipient SSNs into a consumer chatbot |
| Log what the model flagged, what the reviewer decided, and why | Discard the trail; a penalty appeal rests on being able to show the process |
| Start validation at vendor onboarding, when the W-9 comes in | Discover the vendor list in January |
What AI cannot do in tax filing, at least today
The limits matter as much as the capabilities, and a firm that understands them will use the tools better.
- It cannot know the facts. Whether a worker is a contractor or an employee, whether a payment is reportable, which entity is legally the payer: these are judgments about the client’s circumstances, and a model has no access to them beyond what it is told.
- It cannot verify a TIN. Only IRS data can say whether a name and number belong together. A model can check the format and nothing more.
- It can be confidently wrong. Extraction models transpose digits and merge columns, and they do so without hesitation. That is why every extracted value needs a visible source and a human reviewer, and why the pipeline in Figure 1 puts deterministic rules after intake rather than trusting the intake.
- It cannot sign. The certifications on a W-9 are made under penalties of perjury, and the declarations a transmitter makes to the IRS are made by a named, responsible person. There is no mechanism for delegating that to software, and no reason to want one.
- It does not know the current law unless told. Thresholds, deadlines, form revisions and penalty amounts change every year. A model carries the law as of its training data, which is why rule tables, not prompts, should hold the figures.
- It raises the data-handling bar rather than lowering it. Sending recipient SSNs to a model is a disclosure to a service provider, with everything that implies under the Safeguards Rule.
The regulatory frame for using AI on taxpayer data
Nothing in the Internal Revenue Code says “AI.” The obligations that apply are older and broader, and they apply with full force to an AI tool.
- The FTC Safeguards Rule. Under the Gramm-Leach-Bliley Act, tax preparers are financial institutions for the rule’s purposes. IRS Publication 4557 spells out what that means: a written information security plan, a named person responsible for it, multi-factor authentication for anyone touching customer data, a risk assessment, staff training, and oversight of service providers, including a contract that requires them to maintain safeguards. An AI vendor that receives recipient data is a service provider under that rule.
- Section 7216 and section 6713. For firms that also prepare income tax returns, these sections restrict the disclosure and use of tax return information. Routing that information through a third-party model is a disclosure, and the firm needs to be able to show it was a permitted one.
- Circular 230. Practitioners must exercise due diligence in preparing and filing documents with the IRS. The duty does not transfer to the software. A practitioner may rely on a tool, but is responsible for the result.
- Backup withholding and penalty rules. Publications 1281 and 1586 describe the B-notice procedure and the reasonable-cause defense to information return penalties. Both rest on documentation: dated solicitations, dated responses, and a record of what was checked. An AI-assisted process should generate that record as a by-product, not as an afterthought.
- Independent assurance. A SOC 2 attestation, encryption at rest and in transit, and a stated retention period are the questions a firm should be asking any filing or AI vendor before the first SSN is uploaded. We hold a SOC 2 Type I attestation and encrypt all data at 256 bits, and we publish our controls on a public trust center so that the answers do not depend on a sales call.
Where this is going
Three shifts are already visible. The first is on the IRS side: the move from FIRE to IRIS replaces a fixed-width file format with structured XML and faster acknowledgements, which means more errors can be rejected at the gate and reported back within hours rather than weeks. Pre-filing validation will matter more, not less, because the IRS will be checking more.
The second is on the intake side. The gap between “here is a spreadsheet” and “here is a reviewable table of forms” is closing quickly, and the next generation of filing tools will accept a vendor export, a photo of a form or a plain-language instruction and produce the same flagged rows that today take a template. The human review step does not go away in that picture. It becomes the whole job.
The third is regulatory. Expect guidance from Treasury and the IRS on AI in tax practice, and expect it to look like the Safeguards Rule and Circular 230 applied with more specificity: audit trails, human accountability, and vendor oversight. Firms that build those into the process now will not have to rebuild it later.
Common questions
Can AI file 1099s automatically?
AI can prepare, validate and flag them. The transmission to the IRS is made by an authorized transmitter after a person approves the batch, and the certifications involved are made by people. Fully unattended filing is neither available nor advisable.
Does AI replace IRS TIN Matching?
No. A model can check that a TIN has the right shape. Only the IRS can confirm that it belongs to the name on the form, and the IRS TIN Matching program through e-Services is the only way to ask.
Is it safe to put SSNs into an AI tool?
Only inside a process that treats the tool’s vendor as a service provider under the FTC Safeguards Rule: a contract, encryption, a retention limit, no training on your data, and multi-factor authentication for everyone with access. A consumer chatbot meets none of those tests.
What is the penalty for a 1099 with a wrong TIN?
For returns filed in 2027, $340 per return under section 6721 and $340 per payee statement under section 6722, reduced to $60 each if corrected within 30 days and $130 each by August 1, and raised to $680 each for intentional disregard. Documented TIN solicitations support a reasonable-cause waiver.
The point of all of it
Automation did not make information-return filing accurate; it made the errors visible earlier. AI extends that by reading what rules could not and noticing what rules were not written for. Neither replaces the person who looks at the flagged row, decides, and signs. The firms that get the most from these tools are the ones that keep that person in the chair and give them a shorter list to look at.
Sources
IRS instructions for Forms 1099-MISC and 1099-NEC
IRS general instructions for information returns
IRS instructions for Forms 1094-C and 1095-C
IRS Publication 1281, backup withholding
IRS Publication 1586, reasonable cause
IRS Publication 4557, safeguarding taxpayer data
About the author
Taposhi Amin holds an MS in Public Administration and brings extensive experience in compliance and operations to her work with Tax Form Hero LLC, which operates TaxFormHero, an IRS-authorized e-filing platform for 1099, W-2 and ACA information returns. She writes about automation, data governance and regulatory compliance for the businesses and firms that file them.